Roofing Service
Roof Insurance Claims Assistance in Valparaiso, Indiana
A storm claim can pay for a roof you’d otherwise have to fund yourself — but only if the damage is documented properly and the scope reflects the true loss. Most homeowners have never filed a roof claim and don’t know what an adjuster needs to see, which is exactly where a good roofer earns their keep: we document the damage the way the process requires and make sure nothing legitimate gets left off the scope.
- Locally Owned in Valparaiso
- Licensed & Insured
- 24/7 Emergency Response
- Free, No-Pressure Estimates
A storm claim can pay for a roof you’d otherwise have to fund yourself — but only if the damage is documented properly and the scope reflects the true loss. Most homeowners have never filed a roof claim and don’t know what an adjuster needs to see, which is exactly where a good roofer earns their keep: we document the damage the way the process requires and make sure nothing legitimate gets left off the scope.
We help Valparaiso and Porter County homeowners through the whole claim — from the first dated photos to meeting the adjuster on-site to restoring the roof to the approved scope. We do it the honest, Indiana-compliant way: we never waive your deductible, never promise a “free roof,” and never inflate a claim. The insurer decides coverage; we make sure the decision is based on complete, accurate documentation.
How we help with your claim
- Free storm inspection to determine whether you have a claim-worthy loss.
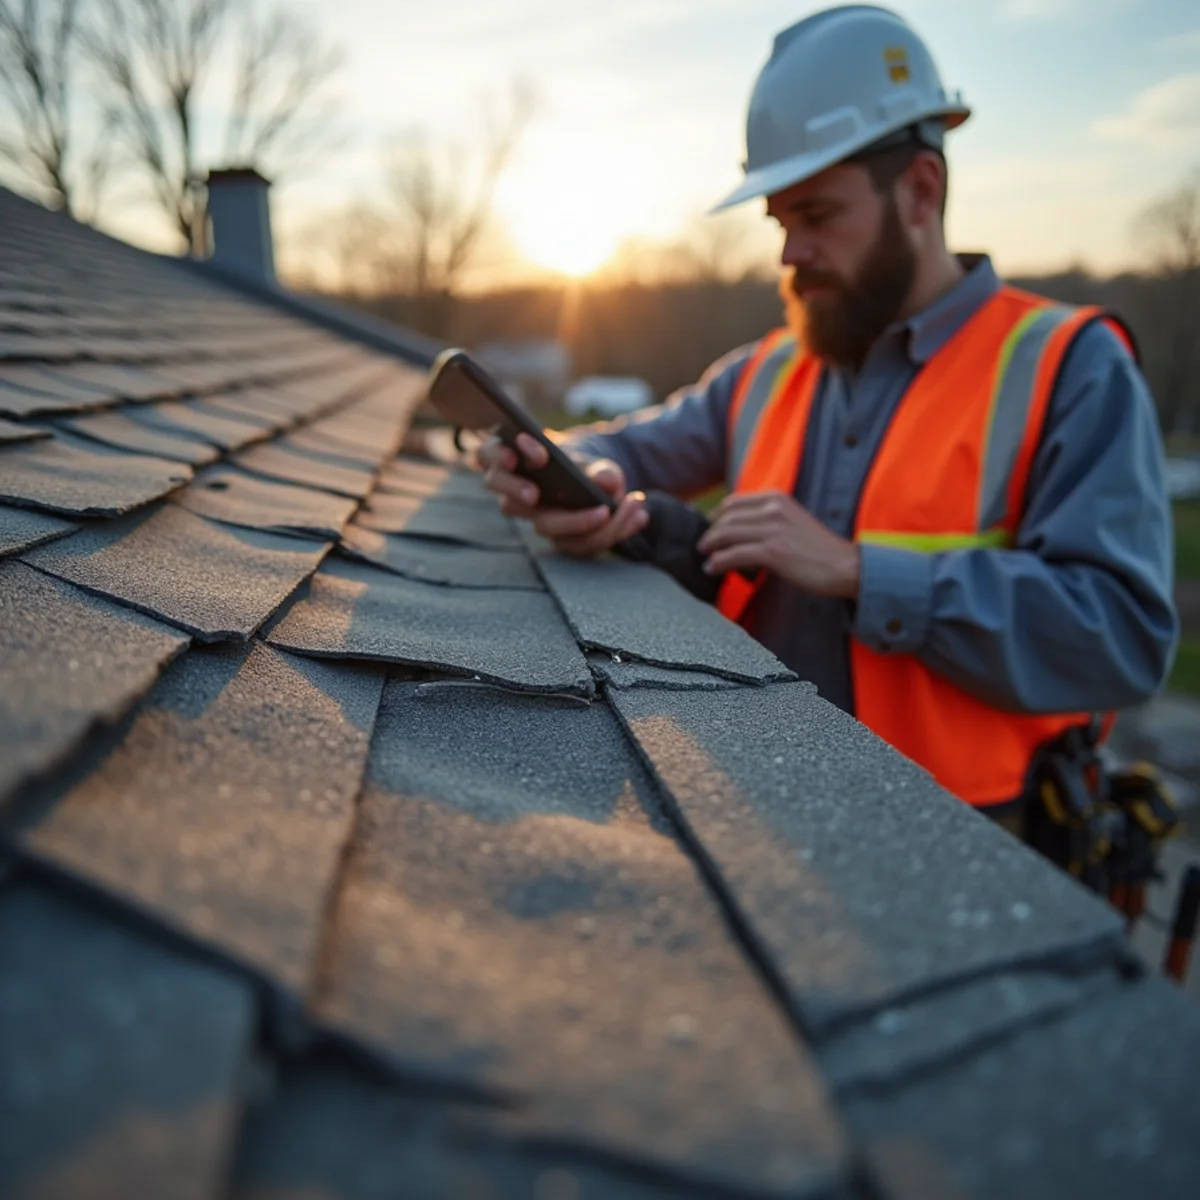
- Dated, itemized photo documentation of every damaged elevation and component.
- A written, insurance-ready estimate an adjuster can verify.
- On-site presence when your adjuster inspects, so the scope is complete.
- Help understanding RCV vs. ACV and how depreciation is recovered.
- Restoration to the approved scope with a registered warranty.
What’s Included With Your Insurance Claims in Valparaiso
No vague “we’ll fix the roof.” Here’s what you get on the job, spelled out before we start:
- A free inspection to determine whether you have a claim-worthy loss
- Dated, itemized photo documentation of every damaged component
- A written, insurance-ready estimate an adjuster can verify
- On-site presence when your adjuster inspects the roof
- Help understanding RCV vs. ACV and recoverable depreciation
- Reconciliation of the insurer’s scope against the true damage
- Restoration to the approved scope with registered warranty
- A clear, Indiana-compliant process — your deductible always disclosed, never waived
The claim process, step by step
- 1
Inspect first
We inspect and document before you file, so you know whether the damage warrants a claim.
- 2
File with evidence
You file the claim with dated photos and our estimate already in hand.
- 3
Meet the adjuster
We’re on the roof with your adjuster so legitimate damage isn’t missed and the scope is fair.
- 4
Restore & reconcile
We complete the approved work and provide final documentation to recover any withheld depreciation (on RCV policies).
Indiana deductible law — and why “free roof” offers are a trap
Indiana law prohibits a contractor from paying, waiving, absorbing, or rebating your insurance deductible. When a storm-chaser promises a “free roof” or offers to “eat your deductible,” they’re proposing an arrangement that isn’t legal here — and one that usually hides inflated pricing, cut corners, or a claim that falls apart under scrutiny. Your deductible is your share of the loss, full stop.
Honest claim help looks different. It means an accurate estimate, thorough documentation, an on-site adjuster meeting, and a roof restored to the approved scope by a local contractor who’ll honor the warranty. We’ll tell you plainly whether you have a claim, what your deductible will be, and how RCV depreciation gets recovered — no gimmicks, no pressure.
Why Valparaiso Homeowners Choose Anto for Insurance Claims
We document before you file
We inspect and photograph first, so you know whether the damage is genuinely claim-worthy before you ever open a claim.
An estimate an adjuster can verify
A clear, itemized, insurance-ready estimate — not a bottom-line number — so the approved scope reflects the true loss.
We’re on the roof with your adjuster
Being on-site during the adjuster’s inspection is where legitimate damage stops getting missed and the scope gets fair.
Indiana-compliant, no gimmicks
We never waive your deductible or promise a “free roof” — both are illegal or dishonest here. Just accurate documentation and honest help.
The claim money homeowners leave on the table
The most common way homeowners short themselves on a storm claim is by not understanding recoverable depreciation. On a replacement-cost (RCV) policy, the insurer’s first check is the depreciated amount — they hold back the depreciation until the work is actually done. You recover that remaining balance only after the roof is completed and the final invoice is submitted for reconciliation. Homeowners who take the first check and never finish the work simply forfeit the rest.
Supplements are the second piece people miss. An adjuster can only scope what they can see from the ground and the surface; once we begin a full tear-off, hidden conditions often surface — rotted decking, an extra buried layer, damaged flashing — that legitimately weren’t in the original estimate. A documented supplement request gets the scope and the payment corrected for what the roof actually needs.
Finally, ask about ordinance-or-law coverage. Building codes change, and today’s code may require ice-and-water shield, drip edge, or other upgrades the original roof never had. Ordinance-or-law coverage, when your policy includes it, pays for those code-driven additions rather than leaving you to fund the gap. None of this means a free roof — your deductible is always yours under Indiana law, and the insurer decides coverage — but complete documentation is what gets a fair claim paid in full.
The mistakes that sink an otherwise valid roof claim
A legitimate claim can still be denied or underpaid when the homeowner mishandles the process, and the errors are usually avoidable. The most common is cleaning up or repairing the damage before it’s documented — hauling off the shingles in the yard, or having a quick patch done, erases the evidence an adjuster needs to tie the loss to the storm. Photograph everything first. The second is waiting too long: policies set filing deadlines, and the longer the gap between the storm and the inspection, the easier it is for a carrier to argue that a later event or plain wear caused the damage.
Getting the storm date and cause right matters too. Attributing damage to the specific event the National Weather Service Chicago warnings recorded — rather than a vague “sometime this spring” — keeps the claim on solid ground. So does starting with a dated hail inspection before you file, so you open the claim already knowing whether the damage is real and claim-worthy instead of triggering a denial that stays on your record.
Finally, read your own policy before you assume. Cosmetic-damage exclusions, roof-age provisions, and ACV settlements all change what a fair outcome looks like. The insurer decides coverage and your deductible is always yours under Indiana law — but avoiding these mistakes is what lets a valid claim be paid as it should be.
What to Expect From the Claim Process — and How to Prepare Before You File
Walking into a roof claim prepared changes how smoothly it goes. Before you file, pull your homeowners policy and find three things: your deductible, whether you carry replacement-cost (RCV) or actual-cash-value (ACV) coverage, and any wind or hail provisions. Note the date of the storm — tying the damage to the specific event the National Weather Service Chicago warnings recorded keeps the claim on solid ground — and gather any photos you took before cleanup. Don’t repair or haul off damage yet beyond emergency mitigation, because a patched roof erases the evidence an adjuster needs to see.
We inspect and document first, so you know whether the loss is genuinely claim-worthy before you ever open a claim. You file with dated photos and our itemized estimate in hand; the carrier assigns an adjuster, and we meet them on the roof so the approved scope reflects the true damage. Filing to an adjuster visit is often a week or two, with reconciliation and scheduling following from there — storm-season backlogs can stretch it. Related storm work like full storm restoration runs on a normal replacement timeline once the scope is approved.
We do it the Indiana-compliant way — your deductible is always yours, we never waive it, and there is no “free roof.” When it’s done, you’ll have a roof restored to the approved scope, the final documentation needed to recover any withheld depreciation on an RCV policy, and a registered warranty.
Understanding what you’ll pay
Every roof is different — these are the factors that move the number. We give you a written, line-item scope after a free inspection. Cost figures are planning benchmarks, not quotes.
- Your deductible — always your responsibility under Indiana law, and never waivable.
- RCV vs. ACV: RCV policies reimburse recoverable depreciation after the work is done; ACV pays depreciated value.
- Any upgrades you choose beyond the covered scope (e.g., impact-rated shingles).
- Non-covered items the insurer excludes from the scope.
- Whether the loss is approved at all — the insurer makes that decision.
Insurance Claims Across Valparaiso & Porter County
We help homeowners through roof insurance claims across Valparaiso and Porter County — hail and wind claims after named storms in Valparaiso, Hobart, and Crown Point, and adjuster meetings throughout Merrillville and the wider Lake and Porter County region.
Insurance Claims FAQs
Related Reading
Related Roofing Services
Storm Damage Roof Restoration
Inspection, documentation, claim support & full rebuilds after hail, wind & derechos.
Learn moreHail Damage Roof Repair
Free hail inspections, photo documentation, and insurance-ready estimates.
Learn moreWind Damage Roof Repair
Torn shingles and lifted flashing repaired fast after derecho and tornado winds.
Learn moreRoof Inspection
Free, documented roof inspections — photo report, honest repair-or-replace call.
Learn moreNeed Insurance Claims in the Valparaiso Area?
Call for a free inspection and a written estimate — or send us a few details and we’ll reach out.
- Licensed & Insured
- 24/7 Emergency Response
- Free, No-Pressure Estimates