The full hail damage insurance claim process for Indiana homeowners, from inspection to final payment, explained step by step.
Hail can look harmless from the driveway and still cut years off your roof's life. Ice stones bruise the shingle mat, knock away the protective granules, and crack the surface in ways that only show up when the roof starts leaking months later. If a hailstorm has moved through Valparaiso, understanding the claim process ahead of time helps you get a fair outcome instead of a headache.
This is the same process we walk homeowners through every storm season. It is not complicated, but the order of steps matters, and a few small mistakes early can slow the whole thing down. Here is how a hail claim works in Indiana from start to finish.
Step 1: Get a Professional Inspection First
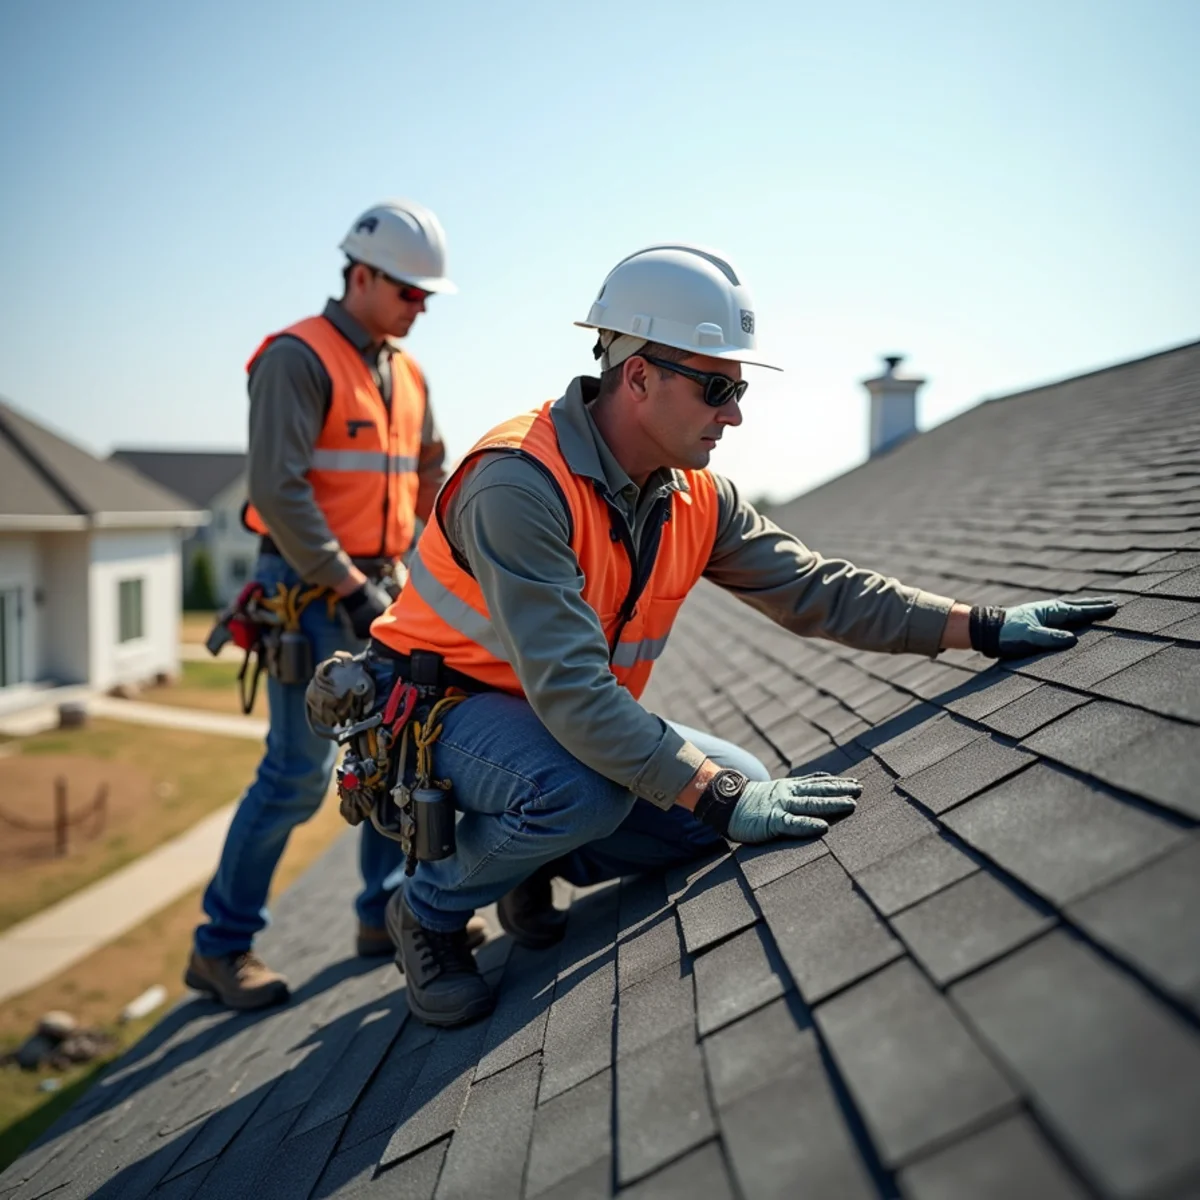
Before you call your insurer, know what you are dealing with. A qualified roofer documents the hail damage with photos, measurements, and a written report, distinguishing true storm damage from normal wear. This matters because you only want to file a claim when there is genuine, documented damage. Our hail damage roof repair inspections give you an honest read before anything goes on your insurance record.
- Bruised or soft spots on shingles from hail impact.
- Granule loss exposing the black asphalt mat underneath.
- Dented gutters, downspouts, vents, and flashing.
- Cracked or split shingles across the slope facing the storm.
Step 2: File the Claim With Your Insurer
Once you have documentation showing real damage, contact your insurance company to open a claim. Give them the date of the storm, and reference any National Weather Service Chicago warnings that were issued for your area, which helps establish the loss event. The insurer will assign a claim number and schedule an adjuster to inspect the roof.
Step 3: Meet the Adjuster
The insurance adjuster comes out to verify the damage and estimate the cost of repair or replacement. It is your right to have your roofer present for this inspection, and we strongly recommend it. The adjuster and your roofer can walk the roof together, agree on what is damaged, and make sure nothing is missed. This single step prevents most disputes down the line. Our team handles adjuster meetings as part of our roof insurance claims support.
Step 4: Understand the Estimate and Your Deductible
After the inspection, the insurer issues a scope of work and an estimate. This is where you need to understand two numbers: the total covered amount and your deductible. Your deductible is the portion you pay out of pocket, and under Indiana law it cannot be waived, absorbed, or paid by your contractor. Any roofer who offers you a free roof by eating the deductible is asking you to break the law, and that is a red flag to walk away.
In Indiana, the homeowner’s deductible is always the homeowner’s responsibility. A legitimate contractor will never offer to absorb or waive it.
RCV and the Two-Check System
Most policies pay replacement cost value, or RCV, in two installments. The first check covers the actual cash value, which is the depreciated worth of your old roof. After the work is complete, the insurer releases the recoverable depreciation as a second check. You can read more about how this works in our guide on RCV versus ACV roof payouts. For planning, a typical Indiana asphalt replacement runs around 15,991 dollars on an average 2,632 square foot roof, though your roof's size and pitch move that number.
Step 5: Complete the Work and Collect Final Payment
Once you approve the scope, the work is scheduled and completed. Your roofer submits the final invoice and any supplemental items discovered during the tear-off, such as damaged decking that was hidden under the old shingles. The insurer then releases the depreciation, and your only out-of-pocket cost is your deductible. Homeowners across Porter roofing service areas rely on us to keep this final stage clean and documented.
The Bottom Line
A hail claim in Indiana follows a clear path: inspect, file, meet the adjuster, understand the estimate and your deductible, then complete the work and collect the final payment. Do it in that order, keep your roofer involved, and never trust anyone who offers to make your deductible disappear. If hail has hit your home anywhere in Valparaiso roofing and Porter County, call Anto Roof Replacement & Repair at (855) 705-1940 for an honest inspection and steady guidance through the claim.
What Happens When the Adjuster and Your Roofer Disagree on the Damage?
It happens more than homeowners expect. Your roofer counts hail hits across the slope and calls for a full replacement; the adjuster writes it up as a repair to two slopes and moves on. This is not necessarily bad faith. Adjusters carry heavy storm-season caseloads and work from their carrier's guidelines, while your roofer is standing on your specific roof. When the two scopes do not match, you have a normal, workable process ahead of you, not a dead end.
How the Disagreement Gets Resolved
- Your roofer submits a written supplement with photos, a hail-hit test square, and line items the original scope missed.
- The carrier reviews the supplement and often approves added items like decking, drip edge, or code-required ventilation.
- If the gap persists, you can request a re-inspection with both parties present on the roof.
- As a last resort, many policies include an appraisal clause to settle a stubborn dispute without a lawsuit.
The homeowner's job through all of this is simple: stay out of the middle and let the documentation do the arguing. A test square, where a roofer marks a ten-by-ten foot area and counts the hail bruises, turns a subjective debate into a number both sides can see. That objectivity is why we insist on being on the roof with the adjuster during our hail damage roof repair inspections rather than comparing notes afterward.
A supplement is not a fight with your insurer. It is the paperwork that gets the parts of the job the first scope simply missed.
One caution specific to Indiana: no matter how the scope shakes out, your deductible stays yours. A contractor who offers to make up a low appraisal by eating your deductible is proposing fraud, not fighting for you. Honest supplementing works within the claim, and it is how homeowners around Porter roofing service areas get full scopes approved the legal way.
The Missteps That Quietly Sink a Good Hail Claim
Plenty of legitimate hail claims fall apart not because the damage was fake, but because of avoidable mistakes the homeowner made along the way. A valid claim has to be handled as carefully as it is filed, and a few common errors hand a carrier every reason to deny or underpay.
- Waiting too long to file, since most policies require prompt notice and a stale claim is easy to question against the storm date.
- Making permanent repairs before the adjuster inspects, which erases the evidence of what the hail actually did.
- Filing on cosmetic dings alone, which invites a denial and can count against you at renewal.
- Entertaining a contractor who offers to absorb the deductible, an illegal arrangement in Indiana that taints the whole claim.
- Losing the paper trail, from the National Weather Service Chicago warnings to the inspection photos that tie the damage to the event.
The through-line is documentation and timing. File promptly, leave the damage intact until it is inspected, and keep every photo and weather record in one place. That discipline, paired with an honest storm damage roof restoration scope, is what carries a claim to a fair payout. Homeowners across Merrillville service areas who avoid these missteps rarely see the disputes that trip up their neighbors, and whatever the outcome, the deductible remains the homeowner’s responsibility under Indiana law.
What to Ask Your Roofer Before You File a Hail Claim
The inspection before you call your insurer is where a hail claim is won or lost, and the questions you put to your roofer decide how solid your file will be. A good inspector welcomes them, because straight answers are what set an honest claim apart from a guess.
- Is this functional damage or cosmetic? Ask them to show you bruised, granule-stripped shingles, not just dented gutters.
- Did you mark a test square? A ten-by-ten-foot count of hail strikes turns a debate into a number the adjuster can see.
- Which slopes took the hits, and do you have dated photos of each from the ground and the roof?
- Will you be on the roof with my adjuster? Walking it together prevents most disputes and missed supplements.
- How do you handle my deductible? The only correct answer is that it is mine to pay, because Indiana law forbids waiving it.
If any answer is vague, or if the roofer hints at making your deductible disappear, that is your signal to stop and find someone else. A clear, well-photographed inspection feeds directly into our guidance on Indiana’s deductible law and a clean claim file, with the storm tied to the National Weather Service Chicago warnings for the date. Homeowners across Crown Point service areas who ask these five questions up front rarely meet the disputes and denials that trip up their neighbors later in the season.